4.25%
London prime yield (Knight Frank)
Development finance, forward funding, development exit, investment and term debt for build to rent schemes in Ealing. This is finance for the rental scheme as an income-producing asset.
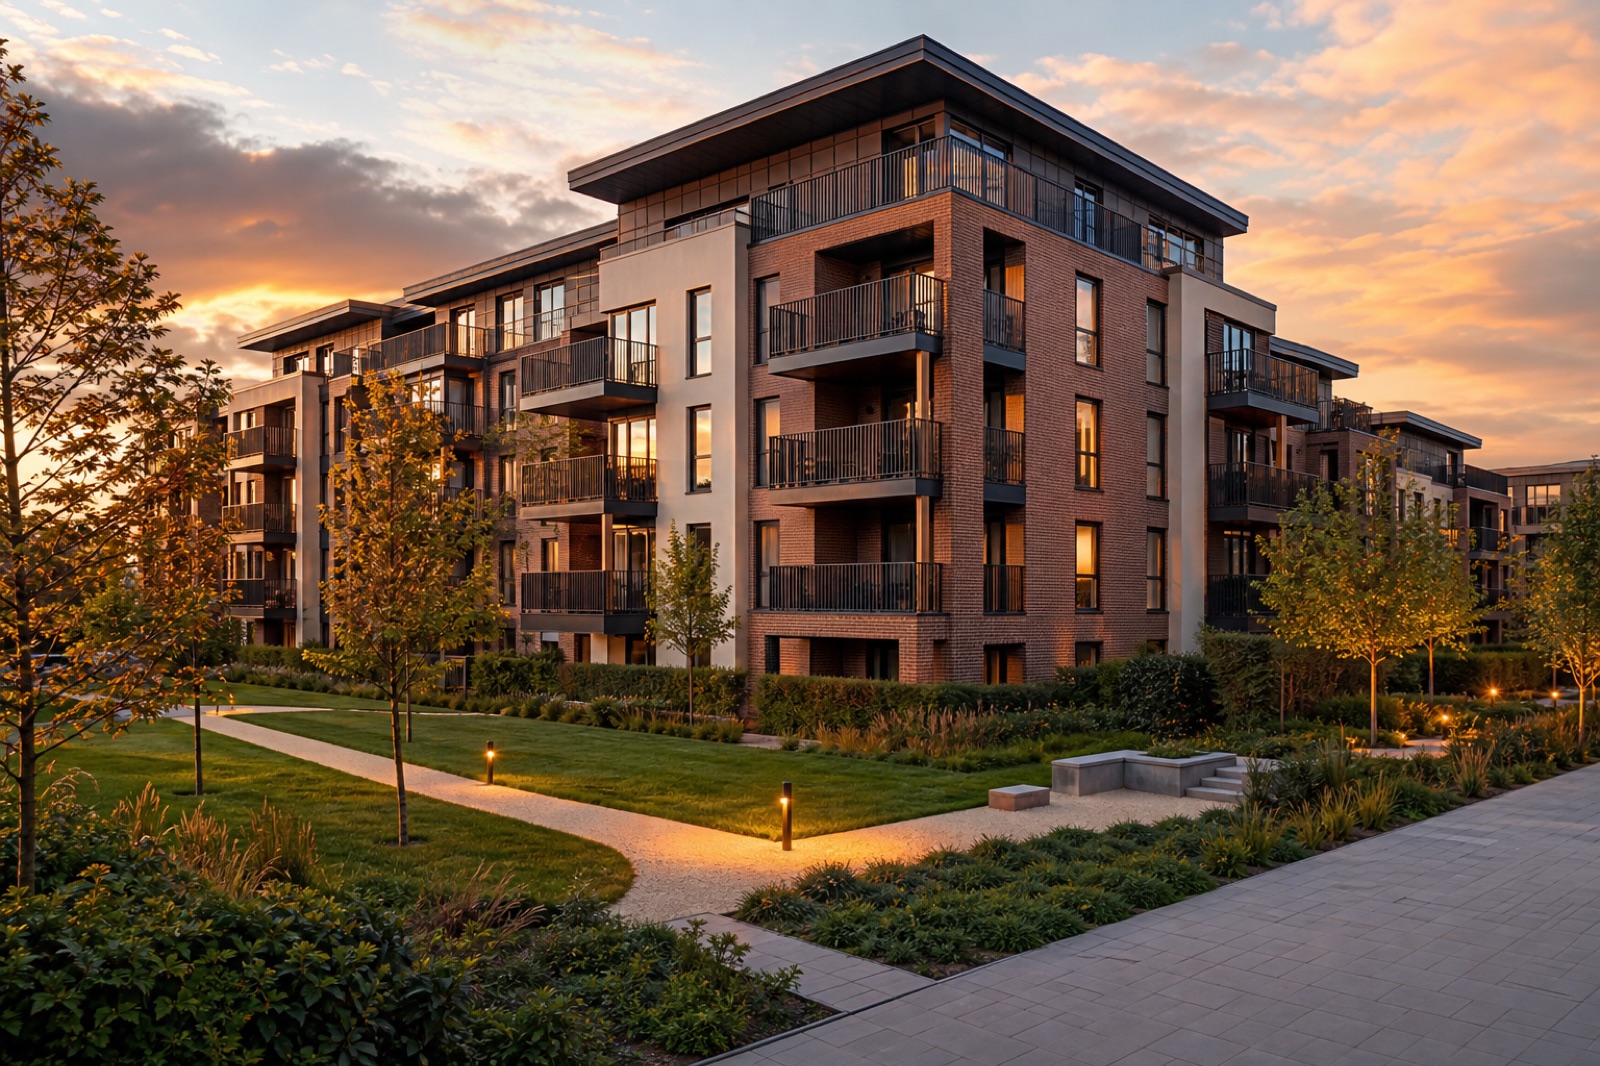
Build to rent finance in Ealing is the funding used to build, forward fund, stabilise or refinance a rental scheme. We arrange it across Greater London for developers, operators and investors, structuring the debt a scheme needs and placing it with the lenders and institutional funders that actually back the private rented sector. This is commercial lending against the scheme and its rental income, sized on the gross development value and the stabilised net operating income.
A Ealing rental scheme is assessed on its appraisal: the land, the build contract, the planning consent, the gross development value and the net operating income the finished homes will produce once let. Prime stabilised stock in the London prices at around 4.25% net initial yield (Knight Frank, Sept 2025), the benchmark a lender and an investor read when they value a Ealing scheme.
We arrange the full range of build to rent finance for Ealing developers and investors. Development finance funds a ground-up build, indicatively to around 60 to 65 percent of cost or 70 to 75 percent of gross development value. Forward funding brings an institutional investor in to fund the scheme up front and buy it on completion. Forward commitment fixes a buyer at practical completion while the developer funds the build. Development exit finance replaces development debt at completion to lower the cost while the homes let up. Investment and term finance sits behind a stabilised, income-producing asset, sized on the net operating income and debt service cover. Bridging moves at site-assembly pace, and mezzanine or equity stretches the leverage where the senior loan will not reach. We match each case to the lenders and funders that back this kind of scheme across Greater London.
Each kind of rental scheme is appraised and underwritten differently, and we arrange finance for all of them in Ealing and across Greater London. That covers multifamily apartment blocks, single-family housing let to families, co-living schemes, regeneration and mixed-use schemes, commercial-to-residential conversions, modular and modern-methods-of-construction schemes, affordable and mid-market rental, and prime build to rent. A multifamily block turns on the stabilised net operating income and the operator. A single-family scheme turns on phased delivery and a portfolio exit. Knowing which lender backs which scheme type here, and at what leverage, is the work we do before a case ever reaches a credit committee. Local planning records show 1 larger residential scheme in the Ealing pipeline, around 31 homes in total, the kind of development that build-to-rent finance funds.
The deepest and keenest-priced BTR market in the UK, though new starts have fallen sharply against viability pressure. The benchmark market on price and liquidity, but constrained delivery: more completions than starts for eight straight quarters, which tightens future supply. Rental growth has run at about 2% (ONS, 12 months to May 2026). Prime stabilised stock in the London prices at around 4.25% net initial yield (Knight Frank, Sept 2025), the benchmark a lender and an investor read when they value a Ealing scheme. The local residential market gives the context a lender reads alongside the scheme: a median sold price of about £517,000 across roughly 2,071 transactions in the last year (HM Land Registry, via the Construction Capital data lake). Lenders and funders read these regional yield, rental-growth and pipeline trends, alongside the scheme's own appraisal, when they size a facility for a Ealing build to rent scheme.
1 larger residential scheme in the London Borough of Ealing planning records, around 31 homes in total, a real read on local development appetite and forthcoming rental supply.
Demolition of the existing buildings and erection of a six storey building with part basement to provide 31 residential units (3 x studios, 23 x one-bed, 5 x two-bed), with associated landscaping, cycle parking and refuse storage
View on the planning portal →Source: local-authority planning records via the Construction Capital data lake, filtered to larger residential development schemes. Live applications, not an indication of consent.
A build to rent scheme is funded against the rent its homes will command and the value of the stabilised income. As local market context, Ealing recorded around 2,071 residential property sales over the past year at a median of £517,000 (active and liquid market), a read on local pricing and demand. The scheme itself is valued on its gross development value and stabilised net operating income, not on these sold prices alone.
Source: HM Land Registry residential price-paid data, last 12 months, via the Construction Capital data lake. Local market context only.
Most development lenders fund up to around 60 to 65 percent of total cost, or 70 to 75 percent of gross development value, capped on the lower of the two. Mezzanine or equity can stretch that toward 80 to 90 percent of cost. The facility is sized on the appraisal, the build cost, the gross development value and the stabilised net operating income, not on a personal income. We hold more than one hundred lender relationships and shortlist the desks most likely to back a Ealing scheme.
We work across challenger and development banks, specialist real-estate lenders, debt funds and institutional forward funders. The right lender for a Ealing scheme depends on the scheme type, the developer's track record and the leverage and structure you need, and we match the case to the desks and funders that actively back it across Greater London.
Prime net initial yields are reported by region and city tier rather than town by town. Prime stabilised stock in the London prices at around 4.25% net initial yield (Knight Frank, Sept 2025), the benchmark a lender and an investor read when they value a Ealing scheme. We read these benchmark figures alongside the individual scheme's appraisal and stabilised net operating income when we structure a facility.
No. We arrange build to rent finance across the whole of Greater London and the wider UK, with the same approach: read the scheme and its appraisal, match the case to the lenders and funders that back the type, and negotiate terms on the borrower's behalf.
Send us the scheme and the appraisal and we will come back with a view on fundability and likely terms within one working day.